Will the financial markets accept the government’s approach to the post Grenfell Building Safety Crisis?
Public Bill Committee Debate – 12th November 2026
“These are the June 2024 figures of life-endangering building defect rates in four of our top house builders—it was on BBC News, and it is published on the Government website. Barratt Redrow has a 35% life-endangering defect rate as per the developer contracts, Bellway Homes 43%, Taylor Wimpey plc 77% and Crest Nicholson plc 69%.” …
“If you have a load of buildings in which all the defects have been ignored by a watered-down remediation standard and all the defects have been left on without any fire performance test evidence, do you not think that the insurers or the lenders might have picked that up? They are watching today. What I am saying is that if we want to contain this, we really need to recognise that those alarming defect rates I have just quoted to you, which are all available in the public domain, mean that there could be litigation in relation to the UK mortgage-backed securities that are sold to anyone who wants to buy them. Credit, insurance and other derivatives related to UK mortgage-backed securities could blow up.”
“My buildingsafetyscheme.org team and I have analysed the prospectuses of some of the leading bonds in mortgage-backed securities, and some do not even mention the credit risk of the non-cladding liability; some mention the cladding liability, but do not mention the non-cladding liability; and some do not mention any liability at all. These are all linked to UK residential mortgages, so they are not being honest in the documentation that they sell bonds on. There is a problem here.”
Horrendous life endangering defect rates in blocks of flats as per UK government data:

UK Government response to defect rates like the above in upcoming legislation
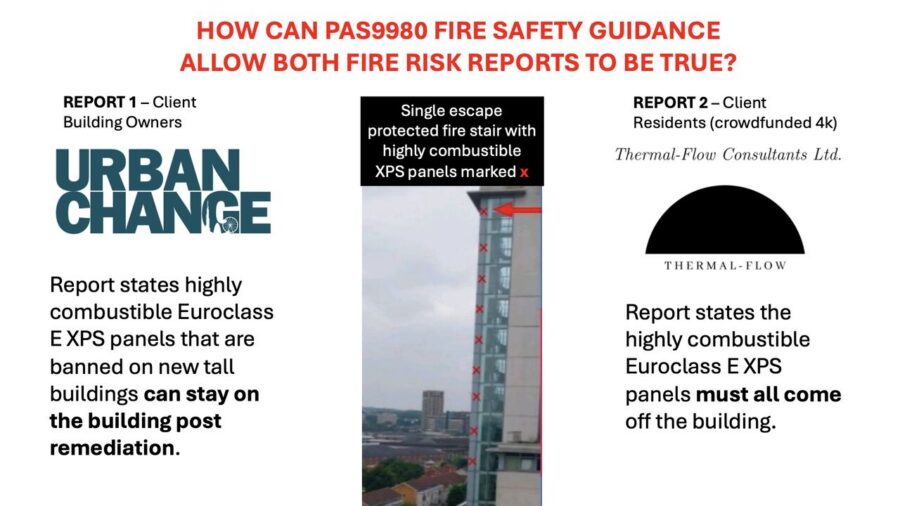
Instead of remediating unlawful fire safety defects on UK blocks of flats and ensuring banned combustibles are only retained on buildings if there is fire performance test evidence to know the risk of leaving it on. The government want to enshrine in law PAS9980:2026, a remediation methodology that allows fire risk assessors to ignore unlawful defects and leave highly combustible banned material on UK blocks of flats without any fire performance test evidence to know the risk of leaving it on.
The insurers were excluded from the PAS9980:2026 working group and have rejected this watered down PAS9980 remediation methodology, confirming it will mean permanently high insurance as buildings aren’t being remediated properly.
There is also a risk of rolling remediations as PAS9980:2026 has a highly subjective approach to remediation determining “tolerable” as the acceptable standard to remediate to. Because the methodology can ignore unlawful fire safety defects and the need for fire performance test evidence, it is likely further remediations will be required. Infact, PAS9980:2026 encourages remediations to be continued after the first tolerable remediation, to bring down the risk to low at a later date. Likewise, as fire risk assessments are carried out every 5 years like EWS1s, there a risk what is considered tolerable for the first remediation is considered medium or high by a later fire risk assessment, requiring another remediation further down the line. When do these remediations stop? Why is tolerable not acceptable to PAS9980 and it encourages a move to low when possible? Who pays for tolerable to low remediations?
Finally there are different levels of exclusions for leaseholders; no protection (buildings <11m, buy to let >=6 properties), partial protections (10k/15k capped leaseholder contributions) and of cause a tolerable remediation standard that risks rolling remediations where there is no certainty to a permanently remediated building.
All of this puts mortgages for UK blocks of flats at risk of valuation reduction and increases the risk of default. Bond prospectus’s on UK residential mortgages aren’t giving the full picture of these liabilities and are not consistent with each other. The risk of UK blocks of flats being deemed “permanently impaired” under Basel 3.1 banking regulations requiring more capital for associated mortgages is also a consideration, given the PAS9980:2026 “tolerable” approach, leaseholder exclusions and rolling remediations.
Post Grenfell Building Safety – The reforms we are calling for:
- All leaseholders should be protected from cladding and non cladding costs. Paid for by increasing the levy to include build to rent builders and product manufacturers (VAT).
- Where a building has fire defects that are breaches of building regulations at the time of construction, then the home owner hasn’t been sold what they paid for and the defects must be remediated to current regulations as the builder broke the law.
- Where a building has fire defects that weren’t unlawful at the time of construction, the defects must be remediated to an as low as reasonably practicable standard. Fire performance test evidence is required for any combustible material to be retained in a fire risk assessment in buildings above 11m.
Will the government act and remediate properly before the markets force them too?